
Art practice — International circulation

Import & export
of works of art

The import and export of works of art in France fall under a triple set of rules: (1) an export certificate for cultural goods (Code du patrimoine art. L.111-2) and an EU licence (Regulation (EC) 116/2009) on departure; (2) a customs declaration with 5.5% VAT on import (CGI art. 278-0 bis, I, and 278-0 B, I); (3) a lawful-provenance check under Regulation (EU) 2019/880 and the international conventions (UNESCO 1970, UNIDROIT 1995). An incorrect characterisation exposes the parties to seizure, customs penalties, or even nullity of the transaction.

Paris · Geneva · Marseille · Cannes · Lisbon
— In brief
What
Customs, tax and heritage regimes for the international circulation of works
For whom
Galleries, auction houses, collectors, specialist shippers, foundations
Key texts
Code du patrimoine art. L.111-2 ; Regulation (EC) 116/2009 ; Regulation (EU) 2019/880
Certificate lead time
4 months from a complete file; silence in principle means the certificate is granted (Code du patrimoine art. R.111-6)
Recommended action
Provenance audit + upstream structuring of every Geneva · London · New York flow
— 01

Three legal layers overlap at every movement

Moving a work of art means answering three questions at the same time: (1) is the item a national treasure whose departure is prohibited or subject to authorisation (Code du patrimoine art. L.111-1)? (2) Which customs and VAT regime applies to the operation (import, export, re-export, inward processing)? (3) What is the lawful provenance and the compliance with the international conventions protecting cultural goods?

A single one of these three layers handled poorly triggers a major risk: refusal of the export certificate, blocking at customs, seizure for lack of lawful provenance, VAT reassessment, or even criminal proceedings (Code du patrimoine art. L.114-1 et seq.).

The firm secures these flows for galleries, auction houses, collectors, foundations and specialist shippers, in France and internationally, with a Paris · Geneva · London · New York coordination.

— 02

The four regimes for the circulation of works

01

Export certificate

A mandatory document to take out of French territory, temporarily or permanently, a cultural good that reaches the thresholds of annex 1 of the Code du patrimoine (for example, a painting over 50 years old, no longer owned by its creator, worth EUR 300,000 or more).

  • Processing time: 4 months from a complete file; silence from the administration in principle means the certificate is granted
  • Refusal reserved for national treasures, after the opinion of a commission: any new application is inadmissible for 30 months, and the State may make a purchase offer
  • Valid without time limit; twenty years, renewable, for goods one hundred years old or less
  • Temporary exit for an exhibition, restoration or expert examination: a temporary exit authorisation instead of the certificate
02

EU export licence

In addition to the French certificate, this is required to take out of the European Union a cultural good covered by Regulation (EC) No 116/2009.

  • Annex I of the Regulation sets 15 categories with their own thresholds, sometimes lower than the French ones: EUR 150,000 for a painting, EUR 50,000 for a sculpture, EUR 15,000 for a photograph
  • Issued by the Minister of Culture (Code du patrimoine art. R.111-19)
  • Presented to customs together with the certificate or the temporary exit authorisation
03

Import from third countries

A reinforced regime since Regulation (EU) 2019/880: an import licence for certain sensitive categories, an importer's declaration for others.

  • Export in accordance with the law of the country where the good was created or discovered; where that country cannot be determined, or for an exit before 24 April 1972, the law of the last country where it was located for more than five years
  • Archaeological goods and elements of dismembered monuments over 250 years old: licence; other categories over 200 years old and worth EUR 18,000 or more: importer statement
  • Licences and statements filed through the ICG electronic system, mandatory since 28 June 2025 at the latest
04

Special customs regimes

Temporary admission, inward processing, transit, customs warehousing: regimes useful for exhibition, restoration, auction sale or storage in a free port.

  • Temporary admission (exhibition) and inward processing (restoration): with duties and VAT suspended
  • Free port (Geneva, Luxembourg): VAT suspension until release for consumption
  • Discharge: justify the exit or the release for consumption
— 03

France · Switzerland · EU coordination: 5 operational cases

Circulation along Paris ↔ Geneva ↔ London ↔ New York requires precise coordination of the customs, tax and heritage regimes.

1. Purchase in Geneva to Paris

Import from a third country: customs declaration, 5.5% VAT (CGI art. 278-0 bis, I, and 278-0 B, I) on the customs value plus duties, taxes and incidental costs up to the first place of destination (CGI art. 292), provenance supporting documents, attention to the tax characterisation of the work (CGI annex III art. 98 A).

2. Sale from Paris to New York

Export certificate if the work reaches the annex 1 thresholds, EU licence if it reaches those of Regulation (EC) No 116/2009, export declaration. For a private seller domiciled in France, a permanent export in principle bears the 6% flat-rate tax on the customs value, plus 0.5% CRDS, unless an exemption applies (notably a value of EUR 5,000 or less) or the capital-gains option is chosen, which requires proof of the acquisition date and price; a temporary export remains possible where the sale is uncertain, the certificate still being required. See selling an art collection: advice to the seller.

3. Geneva free port (long-term storage)

VAT suspension as long as the work remains in the free zone. Prepare the exit strategy (local sale, import into France/EU, transfer to another free port). Vigilance on the reporting obligations in France if the holder is a French tax resident.

4. Loan for exhibition (museum, fair)

Work lent for an exhibition abroad: a temporary exit authorisation instead of the certificate (Code du patrimoine art. L.111-2 and L.111-7) and, outside the EU, an export licence. Work coming from abroad: temporary admission with duties and VAT suspended. Nail-to-nail insurance and a loan agreement. The formalities are prepared several months in advance.

5. Restoration abroad

Temporary exit authorisation for restoration (Code du patrimoine art. L.111-2) and, for customs, outward processing: on return, relief may be total or partial, tax being charged in principle on the cost of the restoration, provided the conditions of the procedure are met. Rigorous documentation of the condition and value on departure.

— Map of flows

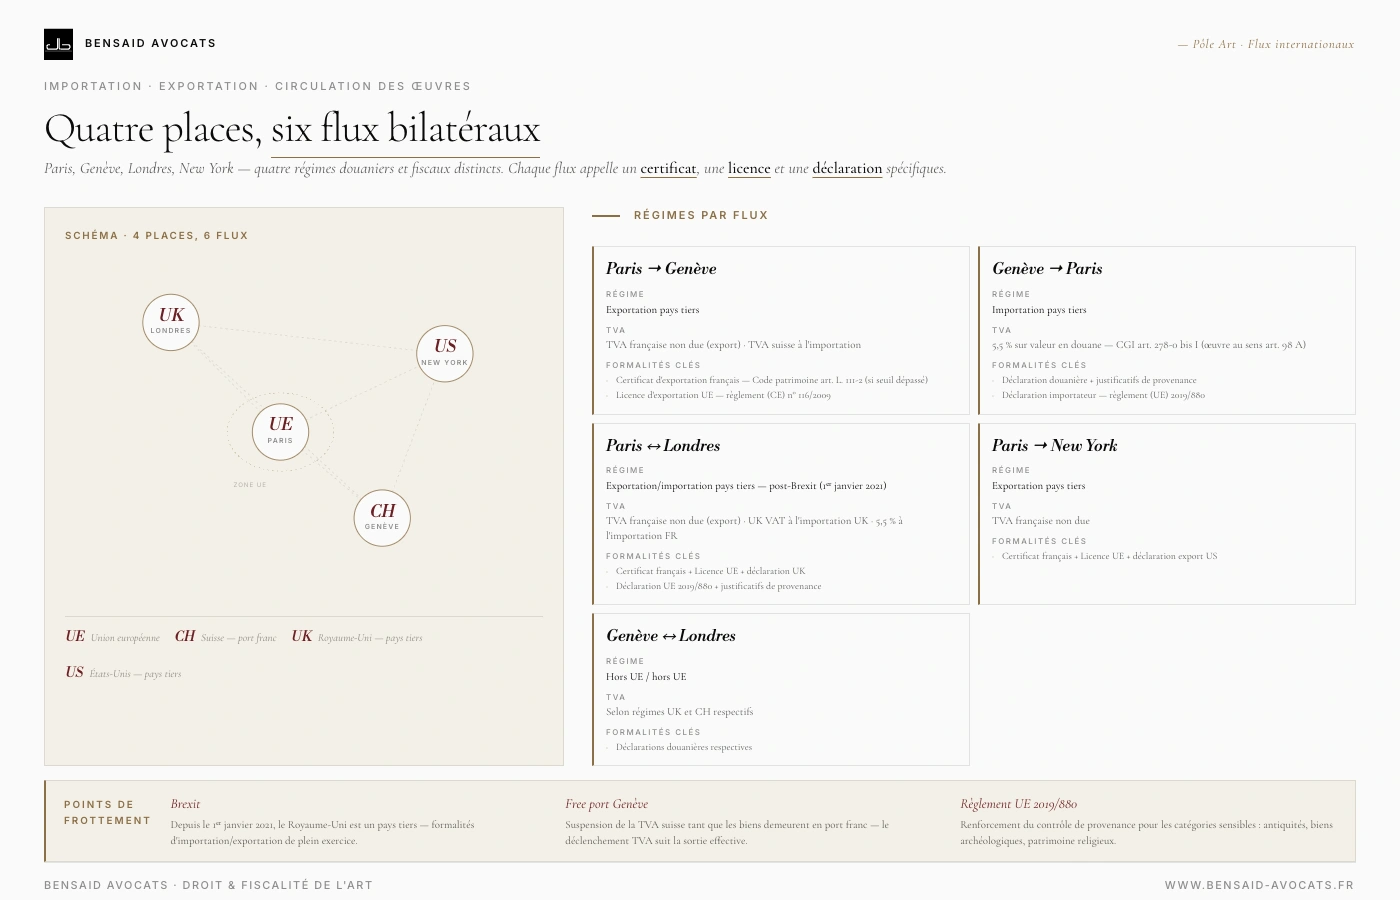
Paris ↔ Geneva ↔ London ↔ New York

Map of the 6 international flows of works of art between Paris, Geneva, London and New York: customs regimes, applicable VAT, export certificates Code du patrimoine art. L.111-2 and Regulation (EU) 2019/880.
Points of friction: Brexit (UK = third country since 2021), Geneva free port (VAT suspension), Regulation (EU) 2019/880 (provenance). © Bensaid Avocats.
— 04

Our experience with galleries, auction houses and shippers

The firm regularly advises galleries, auction houses, international collectors and specialist shippers on cross-border operations involving works of art: preparing export-certificate files, handling certificate refusals and State purchase offers, securing provenance chains, structuring free-port operations (Geneva, Luxembourg), and defence in the event of a customs seizure.

Our dual France · Switzerland bar admission is an operational advantage here: we coordinate directly with the Swiss cantonal authorities, we structure the Paris · Geneva · London flows and we work in a network with New York and London lawyers on transatlantic transactions.

We act both upstream (audit of provenance chains, structuring of operations, pre-acquisition advice) and in litigation (appeals against certificate refusals, customs litigation, defence in seizure procedures under the cultural-goods regulation).

— Frequently asked questions

Moving a work of art safely

What are the thresholds for the French export certificate?

The thresholds are set in annex 1 of the Code du patrimoine (art. R.111-1), in force since 1 January 2021. For works over 50 years old no longer owned by their creator: paintings EUR 300,000, sculptures EUR 100,000, watercolours, gouaches and pastels EUR 50,000, drawings EUR 30,000, photographs EUR 25,000, engravings and prints EUR 20,000. Archives over 50 years old are covered from EUR 300. Above these thresholds, any exit from the territory, even temporary, requires the certificate (or, for an exhibition, restoration or expert examination, a temporary exit authorisation), which may be refused only for a national treasure. The thresholds of the EU licence are separate and sometimes lower (EUR 150,000 for a painting).

What happens if the export certificate is refused?

The refusal, issued after the reasoned opinion of a commission, means that the work has the character of a national treasure (Code du patrimoine art. L.111-4). For 30 months, any new application is inadmissible (art. L.111-6) and the State may make a purchase offer that takes account of international market prices (art. L.121-1). If the owner does not accept it within three months, the price may be set by expert valuation; the State then has two months to offer the valuation price. If the owner refuses that offer, or does not answer within two months, the refusal of the certificate is renewed, with no compensation. Conversely, if the State makes no offer within these time limits, the certificate can no longer be refused. These months can be used to prepare another outcome: sale to an institution, purchase by the State funded by corporate payments that give entitlement to a tax reduction (CGI art. 238 bis-0 A), dation in payment (payment in kind).

What is the difference between the French certificate and the EU licence?

The French certificate authorises departure from French territory (to the EU or to a third country). The EU licence is required to leave the territory of the European Union, in addition to the certificate. For a sale from Paris to New York: both are needed. For Paris to Geneva: French certificate + EU licence (Switzerland is outside the EU).

Is the Geneva free port a tax haven?

No. It is a warehouse under customs control on Swiss territory, where Swiss VAT and import duties are suspended as long as the goods remain there. Holding goods there is lawful, but it does not exempt the owner from the tax obligations of their country of residence: for a French resident, taxation of a sale (flat-rate tax or capital gain), inheritance and gift duties. Nor does it remove the goods from the control of the customs authorities.

What should be done if a work is seized at customs for lack of provenance?

Immediate action: (1) identify the measure (detention, customs seizure, refusal under Regulation (EU) 2019/880) and the remedies attached to it, whose time limits are short; (2) reconstruct the provenance chain (invoices, inheritances, archives, export from the country of origin); (3) discuss the characterisation with customs (lawful import, length of holding, good outside the scope of the regulation). Without supporting evidence, the work may be held for a long time, or even confiscated at the end of customs or criminal proceedings.

What obligations apply to specialist shippers?

A shipper or customs broker that files the declaration in its own name on behalf of the owner (indirect representation) also becomes a debtor of the customs debt (Union Customs Code, art. 77). It therefore rightly requires a complete file: certificate, licence, customs value, provenance supporting documents, insurance. An incomplete file leads to refusal to take on the shipment or to delays.

What are the frequent mistakes in the international circulation of works?

Four major mistakes: (1) an under-valued customs declaration on import (VAT recovery + customs fines + risk of a fraud characterisation); (2) omission of the export certificate for works exceeding the threshold per category (seizure on departure or subsequent litigation); (3) undocumented provenance for antiquities leaving a source country (refusal of release for free circulation under Regulation (EU) 2019/880); (4) confusion between temporary admission and free circulation (VAT payable if the work is not re-exported within the discharge time limits).

How does the Geneva free port work in practice?

The Geneva free port (Ports Francs et Entrepôts de Genève SA) is a warehouse under customs control on Swiss territory. Goods are stored there under a regime of VAT and customs-duty suspension. Exit is possible to: (a) internal Switzerland, with Swiss VAT payable on release for consumption; (b) the European Union, with import, 5.5% VAT in France and a provenance check under Regulation (EU) 2019/880; (c) another third country, with re-export. The tax obligations in France (the owner's tax residence) remain due. The goods are under customs control: the free port is not a place of secrecy.

Does Regulation (EU) 2019/880 apply to all imported works?

No. Regulation (EU) 2019/880 covers only cultural goods created or discovered outside the EU; those created or discovered in the EU are excluded. It distinguishes: (a) an import licence for products of excavations and elements of dismembered monuments over 250 years old, whatever their value (annex, part B); (b) an importer statement, attesting that the good left its country of origin lawfully, for the other categories of annex part C where the good is over 200 years old and has a customs value of EUR 18,000 or more. A modern or contemporary work therefore does not reach these age thresholds. Licences and statements go through the ICG electronic system, mandatory since 28 June 2025 at the latest.

Cité par

A cross-border operation to secure?

A confidential first exchange: provenance-chain audit, certificate preparation or defence in the event of a seizure.








